
emilebidmead0
Over emilebidmead0
Things You Should Know About Mortgage
 De huizenmarkt herschrijft om de paar jaar de regels, en kopers die de vorige regels hebben leren kennen, duiken weer op. onvoorbereid for the new ones. Right now, the rules have changed more than they have at any point in a generation. The buyers who understand that are finding deals. The ones who do not are making expensive mistakes.
The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 betaalt ongeveer $1.686 per maand aan aflossing en rente. Diezelfde lening tegen zeven procent. tariefkosten $2,661. Those numbers explain why the market froze rather than crashed when rates moved higher. Volume collapsed. Prices mostly did not.
Betaalbaarheid, volgens de standaardmaatstaf van welk percentage van mediaan huishouden income goes toward the monthly payment on a median-priced home, is near its worst level since the early 1980s. That is a real problem, and it is not going away quickly. That measure being at a historical extreme does not automatically produce a correction. What it means, practically, is that the buyer who can close confidently has more leverage than the headline numbers suggest.
 Voordat je ook maar één advertentie bekijkt, zorg ervoor dat je je pre-approval locked down. Not a rough estimate. Not a verbal confirmation from a loan officer you met once. A full pre-approval based on verified income, tax returns, bank statements, and a hard credit pull. In this market, a seller who receives an offer without that documentation will not take it seriously.
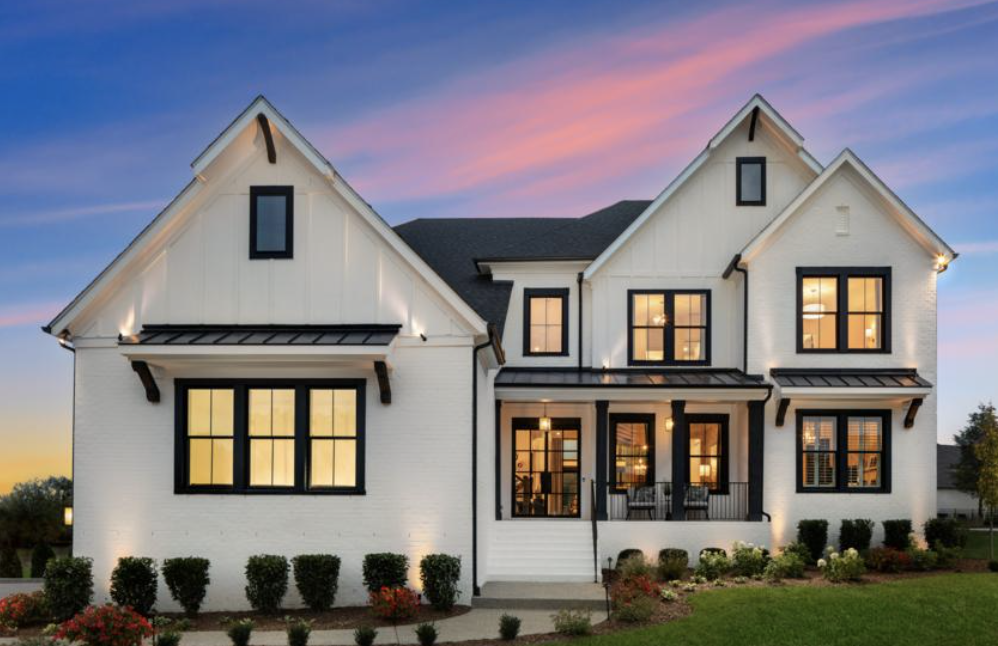 The inspection is where the marketing copy meets reality. Show up for it even if it costs you half a day of work. A good home inspector will walk you through what they are finding as they go, and the conversation is often more valuable than the written report that follows.
 Budget between two and five percent depending on your leningtype and the state you are buying in. First-time buyers routinely underestimate this number. Ask your lender for a Leningofferte zo vroeg mogelijk in het proces.
 The timing question, whether to buy now or wait for rates to come down, is the one that trips up more buyers than any other single factor. The record on market timing for owner-occupied housing is not encouraging. The more useful question is not whether now is the right time in the abstract; it is whether the home works for your actual life for the next five to seven years.
The buyers who come out ahead in this market are not the ones who waited for perfect conditions. They are the ones who understood what they could afford and moved with confidence. Getting across actuele woningaanbiedingen in uw gewenste regio is the logical first move once your financing is sorted.
Geen vermelding gevonden.